Medicare Advantage plans in Tampa Bay, explained in plain English.
Medicare Advantage is a way to get your Medicare coverage through a private insurance company, usually bundled with prescription drug coverage and sometimes extras like dental, vision and hearing. The right plan depends on your doctors, your prescriptions and your budget. There is no charge for our help.
What is a Medicare Advantage plan?
A Medicare Advantage plan, sometimes called Medicare Part C, is an alternative to Original Medicare. It is offered by private insurance companies that are approved by Medicare. I'm Maxwell Kingsbury, a licensed independent insurance agent in Florida, and here is what that means in practice.
Still Medicare
You keep Medicare, but your plan manages your coverage and you show the plan's card at the doctor.
Parts A and B, and usually D
Plans must cover what Original Medicare covers. Most also include prescription drug coverage, though not all do.
Often some extras
Many plans add dental, vision, hearing or fitness benefits. These vary by plan and by year.
A yearly out-of-pocket limit
There is a cap on what you pay for covered, in-network services. Original Medicare alone has no such cap.
You still pay your Part B premium. The plan may have its own monthly premium too, and some plans have a $0 plan premium.
Medicare Advantage vs. Original Medicare with Medigap
Most people choose between two paths. Neither is right for everyone. You can't have a Medicare Advantage plan and a Medigap plan at the same time. Read our Medigap guide for the other path, or start with our Medicare 101 guide for the four parts of Medicare. Prefer something you can print? Download our free Medicare guide.
| Feature | Medicare Advantage | Original Medicare + Medigap |
|---|---|---|
| Who runs it | A private insurer | The federal government, plus a private Medigap insurer |
| Doctors | Usually a network; some plans require referrals | Any doctor or hospital that accepts Medicare |
| Monthly cost | Part B premium plus any plan premium | Part B premium plus a Medigap premium, plus a Part D plan |
| When you use care | Copays and coinsurance set by the plan | Medigap pays most of what Original Medicare doesn't |
| Out-of-pocket limit | Yes, for in-network care | Depends on the Medigap plan, which often covers most costs |
| Extras | Often dental, vision, hearing | Usually separate coverage |
| Drug coverage | Often included | Separate Part D plan |
The plan types you'll see
You will run into a few acronyms. In plain English:
TypeHMO
Health Maintenance Organization. You use the plan's network of doctors and hospitals and usually choose a primary care doctor.
- Referrals to specialists may be required
- Emergencies are covered anywhere
TypePPO
Preferred Provider Organization. You get more flexibility.
- In-network providers cost less
- You can go outside the network, usually at a higher cost
Some areas also offer Special Needs Plans (SNPs) for people with certain conditions or situations, and Private Fee-for-Service plans. Availability varies by county.
What to compare in Tampa Bay
Two plans with the same price can work very differently. These are the questions that matter most.
Are your doctors and hospitals in the network?
Check your primary doctor, your specialists and the hospital you would want to use. This matters more than any premium.
Are your prescriptions covered, and at what cost?
Plans have a drug list (formulary) and a pharmacy network. Your medications and your pharmacy can change the real cost significantly.
What is the out-of-pocket maximum?
This is the most you would pay for covered, in-network care in a year. It is worth a close look if you see doctors often.
Which extras will you actually use?
Dental, vision and hearing benefits only help if you would use them and if your providers participate.
How is the plan rated?
Medicare publishes star ratings for plans. They are one input, not the whole story.
What if you travel or spend part of the year elsewhere?
Many Tampa Bay residents split the year. Network rules matter when you are away.
Networks and drug lists can change from year to year, which is why we check them again before every enrollment period.
When you can enroll or change plans
You can't join or switch plans at any time. These are the main windows. If you're not sure which one applies to you, ask. It is one of the most common mistakes we help people avoid.
First eligibilityAround your 65th birthday
A seven-month window around your 65th birthday.
Annual EnrollmentOct 15 to Dec 7
Anyone with Medicare can join, switch or drop a plan. Coverage starts January 1.
Medicare Advantage Open EnrollmentJan 1 to Mar 31
If you are already in a Medicare Advantage plan, you can switch to another plan or return to Original Medicare once during this period.
Special Enrollment PeriodsAfter certain life events
Moving out of your plan's area or losing other coverage, for example, gives you a window outside these dates.
How we help, and what it costs you
There is no charge for our help. Insurance carriers pay agents a commission when you enroll, so you don't pay anything for our time. The plan costs the same whether you enroll through us or directly.
Request a call
Tell us how to reach you, and we'll call to learn about your doctors, prescriptions and priorities.
Get a personal comparison
We compare the plans we offer against your information and explain the trade-offs in plain English, with no pressure.
Enroll and get ongoing support
If you choose a plan, we help you enroll and we're here for questions after. We also review plans each year, because plans change.
One honest note: We do not offer every plan available in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options.
Common questions about Medicare Advantage
Can I keep my doctor on a Medicare Advantage plan?
Often yes, but it depends on the plan's network. Before you enroll, we check your doctors against each plan's network so you know before you decide. Networks can change, so it's worth rechecking each year.
Do Medicare Advantage plans include prescription drug coverage?
Many do, but not all. Your drug costs depend on the plan's drug list and pharmacy network. We compare this using your actual medications.
Is Medicare Advantage the same as Medicare Supplement?
No. Medicare Supplement (Medigap) works alongside Original Medicare to help pay costs it doesn't cover. Medicare Advantage is a different way of getting your Medicare coverage. You can't use both together.
Can I switch back to Original Medicare?
Yes, during certain enrollment periods. Keep in mind that if you return to Original Medicare and want a Medigap plan, the company may ask health questions in some situations, so it's worth thinking this through before you switch.
What if I move?
Plans are tied to a service area. If you move out of your plan's area, you generally get a Special Enrollment Period to choose a new plan. Tell us if you're planning a move and we'll help you plan ahead.
Do I still pay my Part B premium?
Yes. You continue paying the Part B premium, and your plan may have its own monthly premium on top.
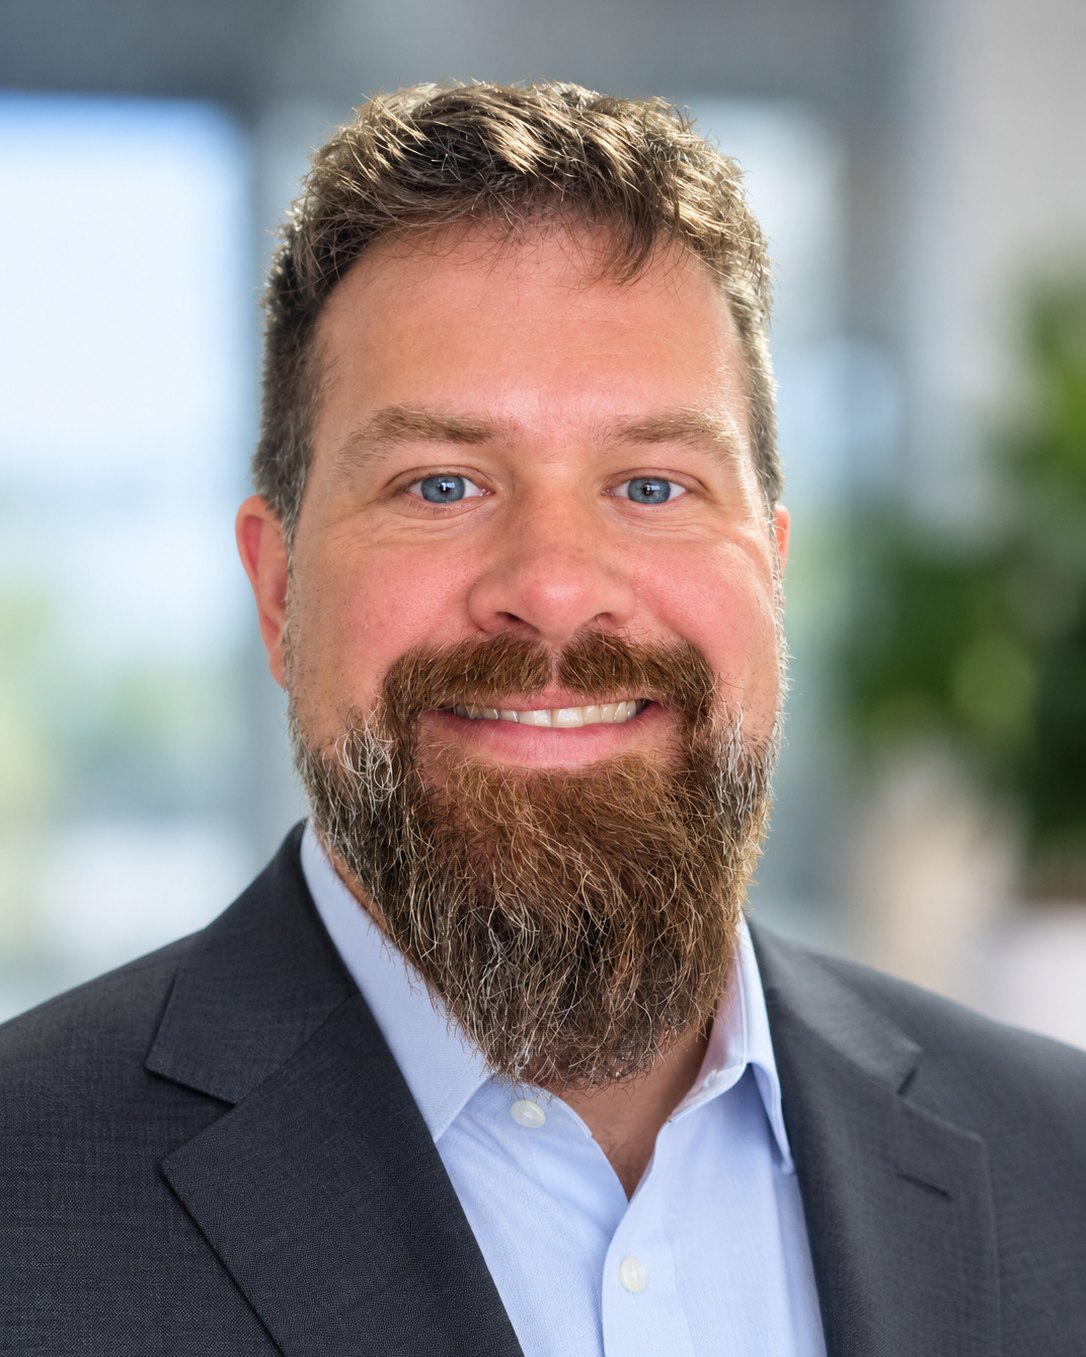
Ready to compare?
Tell Maxwell about your doctors and prescriptions, and he'll show you how the plans we offer line up. It takes a few minutes, and there's no obligation.
Request a call Call Maxwell727-351-3321, 10am-6pm Eastern. See the Privacy Policy.